


Southampton’s first-time homebuyer assistance program now offers up to $171,000 in down payment help, lower monthly housing costs, and a major incentive for volunteer first responders. Here’s what working residents need to know.
Let’s have some real talk about buying a home in Southampton.
For many working people, homeownership here has started to feel less like the American Dream and more like winning the lottery. When homes are selling for $750,000, $900,000 and $950,000, telling someone to “just save for a down payment” can sound almost comical. Save what, exactly, after rent, groceries, childcare, utilities, insurance and everything else that comes with living on the East End?
That is why Southampton’s first-time homebuyer assistance program caught my attention. The Town has increased assistance through its Community Housing Fund from 3% to 18% of a home’s purchase price, up to $171,000.
There is another piece that deserves just as much attention. Qualifying volunteer firefighters and ambulance personnel can have 10% of their Town loan forgiven for each qualifying year of service. After 10 years, the entire loan could be forgiven.
Now we have something worth talking about.
I spoke separately with Southampton Town Councilman Michael Iasilli, who brought the resolution forward, and Southampton Town Housing and Community Development Director Kara Bak. I wanted to get past the government language and answer the questions real people are asking: What does 18% actually mean? Can I find a house? Do I have to repay the money? Who qualifies?
Why Southampton Jumped From 3% to 18%
Sometimes a government program looks great on paper, then hardly anyone uses it.
That is essentially what happened here.
“The 3% assistance wasn’t enough,” Bak told Hamptons Mouthpiece.
According to Bak, approximately $1.25 million had been allocated to the previous program, yet only three people participated. If Southampton wanted its housing dollars to make a meaningful difference, Bak believed the numbers had to change.
The Town Board has now committed an additional $4 million, bringing the amount allocated to a little more than $5 million, according to Bak.
Iasilli says the goal is to reach working residents, including teachers, hospital workers, library employees and others who may be able to handle a mortgage but struggle to overcome the upfront cost of buying.
“This is going to help average working people be able to live where they work,” Iasilli said.
That is where policy starts becoming personal.
What Does 18% Mean in Real Dollars?
Let’s skip the government math and get to the part people actually want to know.
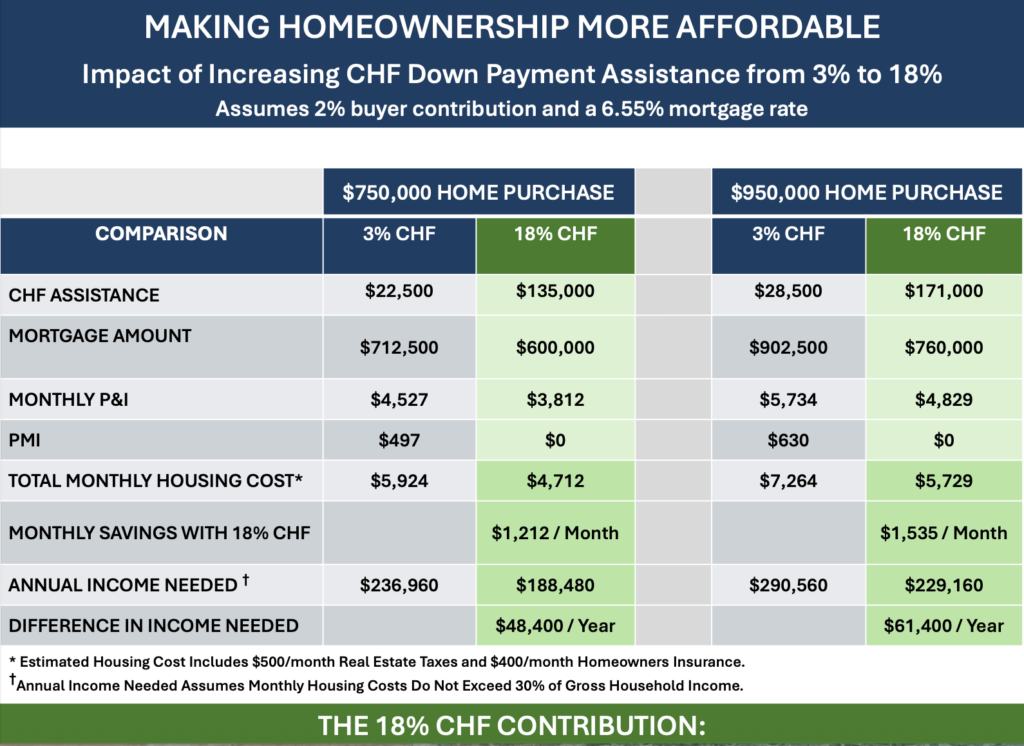
On a $750,000 home, the old 3% program provided $22,500. Under the new program, 18% equals $135,000. With the buyer contributing another 2%, the Town’s example shows the mortgage dropping from $712,500 to $600,000.
Using the assumptions in the Town’s presentation, here is what changes:
- Town assistance: $22,500 becomes $135,000
- Monthly principal and interest: $4,527 becomes $3,812
- Estimated PMI: $497 becomes $0
- Estimated total monthly housing cost: $5,924 becomes $4,712
- Estimated monthly savings: $1,212
- Estimated household income needed: $236,960 becomes $188,480
That last number jumped out at me. In the Town’s example, the estimated income needed to carry the home drops by $48,400 a year.
At a $950,000 purchase price, assistance reaches the maximum of $171,000. The Town’s comparison estimates monthly housing costs dropping by $1,535 and the annual household income needed falling from $290,560 to $229,160.
These are examples, not guarantees. The Town’s calculations assume a 6.55% mortgage rate, $500 per month in property taxes and $400 per month in homeowners insurance. Every buyer’s actual numbers will be different.
Still, $1,200 or $1,500 a month is not pocket change. For some households, that can change the conversation from “absolutely not” to “maybe this is possible.”
The First Responder Incentive Is a Big Deal
This is the part I keep coming back to.
Southampton depends on volunteer firefighters and ambulance personnel. We expect someone to answer when there is a fire, an accident or a medical emergency. Those volunteers, however, are dealing with the same housing costs as everyone else.
Iasilli told me that recruiting and retaining volunteer first responders has become difficult. Southampton is now connecting two community issues that may seem separate at first: housing affordability and public safety.
Here is how it works. A qualifying volunteer first responder can have 10% of the Town loan forgiven for each qualifying year of service.
On that $750,000 home, the Town assistance would be $135,000. Bak explained that $13,500 could be forgiven for each qualifying year. After 10 qualifying years, the entire $135,000 could be forgiven.
At the program maximum, a qualifying first responder could potentially have $171,000 forgiven over 10 years.
“This law now makes it possible for a lot of our volunteer ambulance and firefighters to be able to stay here in the Town, to continue to live here, to start a family,” Iasilli said.
Here is the real talk. We can put up recruitment signs all over town, but at some point we have to ask a practical question: How do we expect people to protect a community they can no longer afford to live in?
If this incentive helps younger firefighters and ambulance volunteers buy homes, raise families here and continue serving, the benefit reaches far beyond one homeowner.
Are There Actually Homes Under $950,000?
I asked Kara this question because, well, this is Southampton.
A $171,000 assistance program sounds fantastic until someone says, “Great. Now show me the house.”
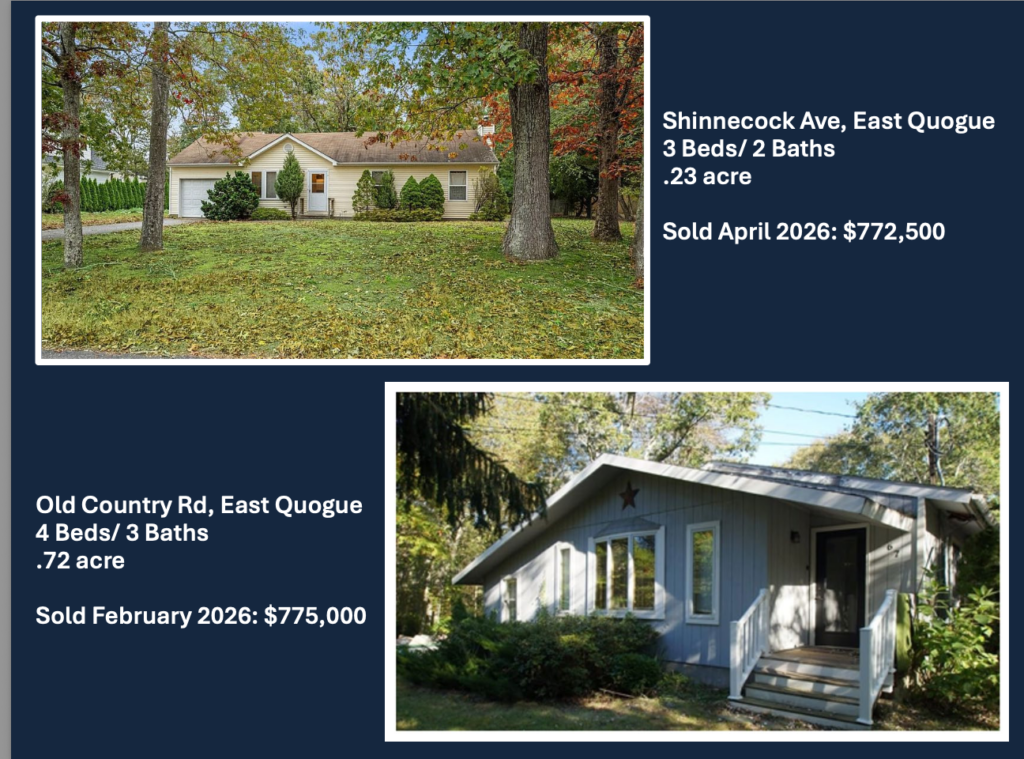
The Town researched actual 2026 sales and identified homes within the program’s targeted price range, including:
- Two East Quogue homes that sold for $772,500 and $775,000
- A North Sea Road home in Southampton that sold for $915,000
- A Southampton Village home that sold for $950,000
- Two Hampton Bays homes that sold for $900,000 and $905,000
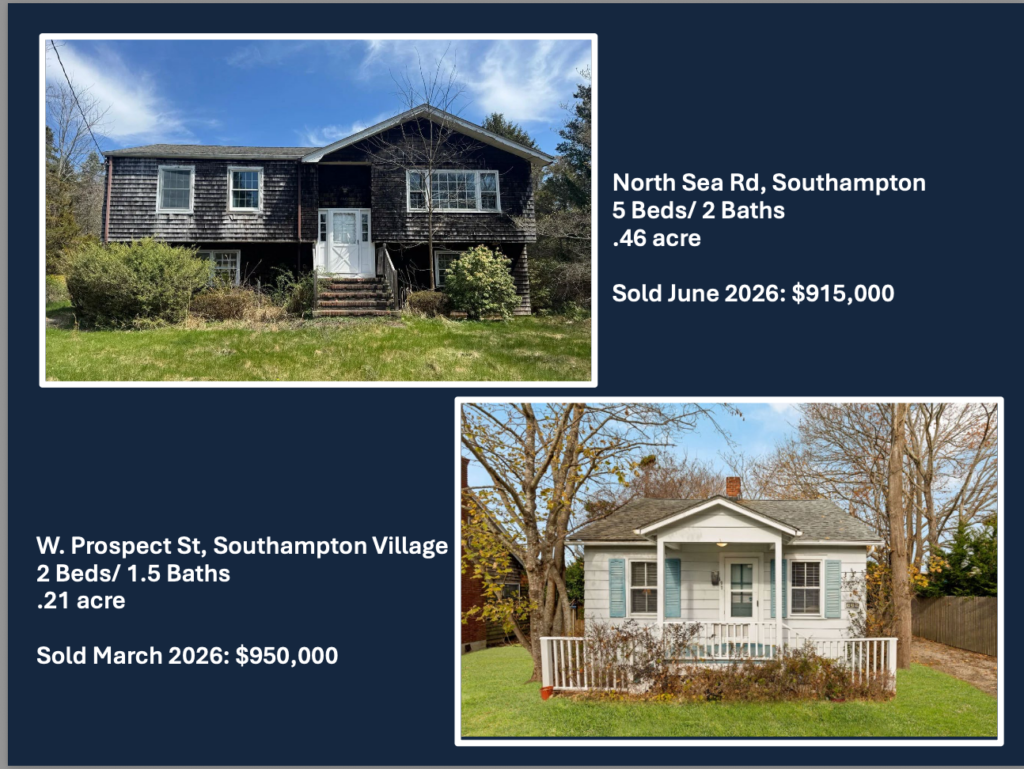
Nobody is suggesting that finding a house under $950,000 in Southampton has suddenly become easy. Inventory, competition, property taxes and mortgage rates remain very real obstacles.
The important point is that these were actual sales, not imaginary houses created for a presentation.
How Does Southampton First-Time Homebuyer Assistance Work?
Southampton’s first-time homebuyer assistance program provides qualified buyers with 18% of an eligible home’s purchase price, up to $171,000, through the Town’s Community Housing Fund.
You cannot stroll into Town Hall and walk out with a $171,000 check. That would certainly make local government more exciting.
Southampton is working with Community Development Long Island, or CDLI, to evaluate prospective buyers. Bak said applicants complete an eight-hour homebuyer education course and are reviewed based on factors including income, assets and debt.
The point is to determine what someone can realistically afford, not simply how much money they would like to spend.
Once qualified, buyers can search for their own home within their approved price range.
“They go out, and then they find their own home,” Bak said.
That flexibility is important. Qualified buyers are not necessarily being placed into a particular housing development. They can search Southampton’s existing housing market for a home that works for them and their family.
Is the Southampton Down Payment Assistance Free Money?
For most participants, no. Bak explained that the Town assistance is a zero-interest loan with no monthly payments. The house must remain the buyer’s primary residence and cannot be rented out.
When the homeowner eventually sells the property, the Town loan must be repaid. Bak said a cash-out refinance can also trigger repayment.
There is an important upside. Bak says buyers using the program to purchase an existing market-rate home can build equity and eventually sell at market value. They repay the Town loan, while retaining the equity they have accumulated.
That means this program is not only about getting through the front door. For some families, it could also provide an opportunity to build household wealth through homeownership.
Qualifying volunteer first responders have the additional possibility of having some or all of the Town loan forgiven through continued qualifying service.
What About People Already Struggling to Stay in Their Homes?
I did not want my conversation with Bak to stop at first-time buyers.
What about the senior on a fixed income who needs a new roof? What about the longtime homeowner who suddenly needs a heating system, windows or other major repairs?
Bak said Southampton works with CDLI to connect homeowners with rehabilitation programs that may assist with needs such as roofs, heating systems and windows. She also pointed to the Town’s Accessory Dwelling Unit program, which she said can provide up to $200,000 to create an ADU on a qualifying property.
That conversation deserves its own article, particularly when we talk about seniors, veterans, residents with disabilities and longtime homeowners living on fixed incomes.
Affordable housing cannot only be about helping people get the keys. It also has to be about helping people keep the keys they already have.
That is real talk about real people.
Real Talk. Now Show Us the Real People.
Southampton recognized that 3% was not moving the needle and increased its first-time homebuyer assistance to 18%. The Town committed another $4 million and created a first-responder incentive that could potentially forgive as much as $171,000.
That is the policy. Now I want to see what it means for the people who actually live and work here.
Iasilli told me that the Housing Department received two inquiries on the same day the measure passed.
The numbers worth watching from here are pretty straightforward:
- How many residents apply?
- How many qualify?
- How many find homes within their approved price range?
- How many actually make it to closing?
- How many volunteer firefighters and ambulance personnel participate?
- How much of the money allocated to the program ultimately reaches homebuyers?
Most importantly, when we revisit this program a year from now, will we be able to sit down with Southampton families who can say, “I own this home because this program gave me a chance”?
That is when a resolution becomes a result. That is when housing policy becomes personal.
That is Real Talk. Real People.
Your Turn, Southampton
If you are a first-time homebuyer who lives or works in Southampton, especially if you are a volunteer firefighter or ambulance member, do not assume you cannot qualify. Ask the questions. Get the numbers. Find out what is actually possible for your household.
I want to hear from you too.
Would 18% down payment assistance change the homeownership equation for your family? If you are a volunteer first responder, would the loan-forgiveness incentive make it easier for you to stay in Southampton and continue serving?
Share this article with the teacher, hospital worker, firefighter, EMT, young family or neighbor who keeps saying, “I work here, but I could never afford to live here.”
Maybe the answer is still no. For some Southampton residents, it may have just become maybe.
Real Talk. Real People. Real Southampton.
other articles on housing: https://hamptonsmouthpiece.com/who-will-do-the-laundry-fixing-the-hamptons-housing-crisis/


Comments are closed.